Market numbers through September 30, 2026. Loan rates as of early October 2026.
If you run a business out of a shop, a warehouse or a yard building between San Antonio and Austin, you have probably asked yourself this question: should I keep renting, or should I buy my own building?
In 2026, that question feels harder than usual. Loan rates are the highest they have been in about 20 years. At the same time, there is more empty industrial space on the market than at any time in the last decade, especially around San Marcos.
Those two facts pull in opposite directions. High rates make buying feel expensive. Empty space gives renters more power than they have had in years.
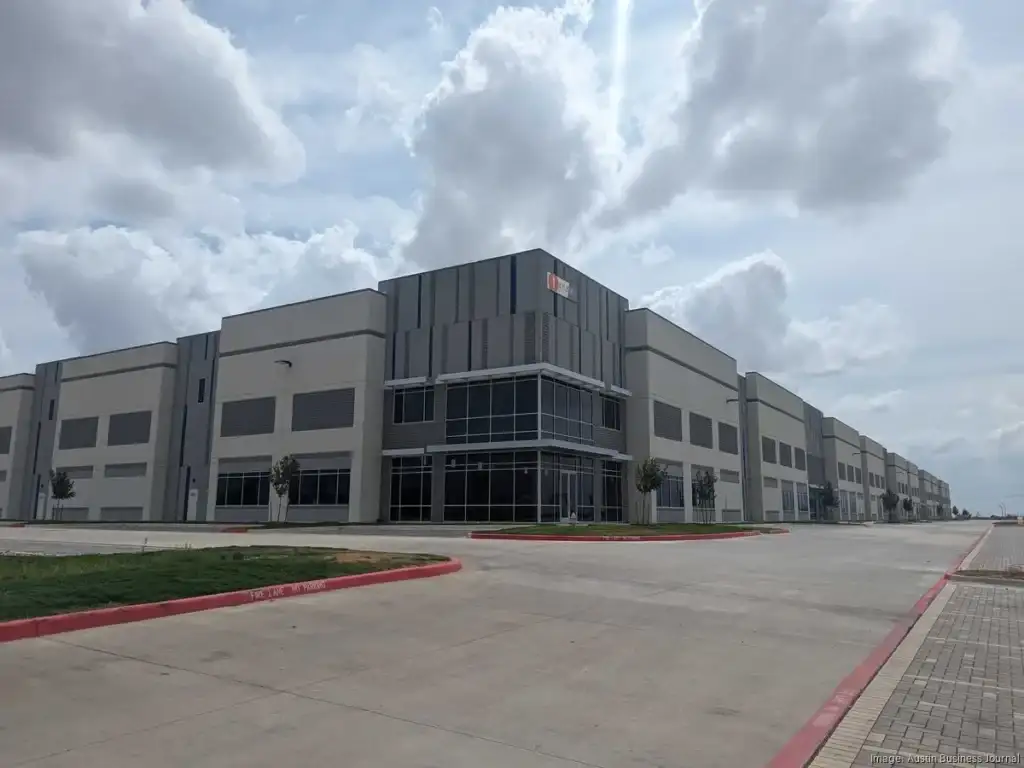
We walk owners through this decision every month. Below, we run the same analysis on one example, a 10,000-square-foot shop, and compare renting and buying in two markets 20 miles apart: the New Braunfels side and the San Marcos side.
TL;DR
- High rates have not made buying a bad idea. With a 10%-down SBA 504 loan, the monthly loan payment on our example shop is about the same as the rent, on both sides of the county line.
- The real hurdle is cash, not the rate. Buying our example shop takes roughly $140,000 to $160,000 down, plus fees and closing costs. That is money that leaves your business.
- Around San Marcos, renters have the upper hand right now. About 18% of industrial space in Hays County is empty, and more is on the way. It is a good time to push a landlord for free months, build-out money or a lower rent.
- Around New Braunfels, buying looks stronger. Less space is empty, rents are still rising, and a fixed loan payment shields you from rent increases.
- A simple rule: if you will stay seven years or more and can spare the cash, buying deserves a serious look. If you need your cash or might move, lease and negotiate hard.
Two markets, 20 miles apart
Our market data is reported by county. So in this article, “the New Braunfels side” means the Comal County industrial market, and “the San Marcos side” means the Hays County industrial market, which also takes in Kyle and Buda.
The two markets are almost the same size, about 23 million square feet of industrial space each (market data through September 30, 2026). But they are in very different places right now.
The New Braunfels side is steady. About 12% of the space is empty. That is a lot more than in 2021, when almost nothing was open. But the number stopped climbing this year and slipped a little. Over the last 12 months, businesses moved into more space than builders added.
The San Marcos side is crowded with new buildings. About 18% of the space is empty, up from 12% a year earlier. More than 2 million square feet of new buildings opened there in the last 12 months. Businesses are still signing leases, but new space arrived faster than tenants could fill it.
Where space is tight, owners hold the cards. Where space is loose, renters do.
How we got here
Five years ago, the story was completely different.
In September 2021, only about 2.6% of industrial space on the New Braunfels side was empty. On the San Marcos side, it was about 5.7% (market data through September 30, 2026). If you needed a shop then, you took what you could find and paid what was asked.
Three things were happening at once. Families and businesses were pouring into the corridor: from 2020 to 2025, Comal County’s population grew about 28% and Hays County’s about 25%, while Bexar and Travis counties each grew about 7% (U.S. Census Bureau estimates, July 2025). Rents were rising close to 9% a year at the peak. And money was cheap, so investors paid top dollar for buildings.
Builders responded. Hays County’s industrial space has grown more than two and a half times since 2016. Comal County’s grew by about half (market data through September 30, 2026). Many of those Hays County buildings were started when the market was tight and finished after it cooled. That timing gap is why there is so much open space around San Marcos today.
Then rates went up. That changed the math for everyone.
What high rates actually changed
Step 1: Rates rose. The 10-year U.S. Treasury rate, which most long-term business loans are priced from, was about 5.3% in early October 2026. That is its highest level in more than two decades. SBA 504 loans, a common way for small businesses to buy their own buildings, priced at about 6.97% for 20- and 25-year terms in October 2026. Regular commercial mortgages were running roughly 6.4% to 7.5%, depending on the lender and the loan size. (Sources listed at the end.)
Step 2: Investors paid less for buildings. When an investor can earn 5% on a safe government bond, they want a lot more than that to own a building with tenants, roofs and repairs. That “more” shows up in the cap rate. A cap rate is a building’s yearly income divided by its price. In September 2021, industrial cap rates were about 6.4% on both sides. Today they are about 7.9% on both sides, the highest in the ten years of our data (market data through September 30, 2026).
Step 3: Prices stopped climbing, even as rents rose. A higher cap rate means a lower price for each dollar of rent. Rents went up about 32% on the New Braunfels side and about 24% on the San Marcos side since September 2021. But the jump in cap rates soaked up almost all of that. If you estimate a building’s value from its rent and the cap rate, a typical square foot on the San Marcos side is worth about what it was in 2021, and only about 6% more on the New Braunfels side. Prices barely moved while rents climbed.
What that means for you. For an owner-user, this is not all bad news. You are paying more for the loan than you would have in 2021. But you are not paying a 2021 premium for the building on top of it. The building costs about the same per square foot as it did then, or a little more, and the rent you would otherwise pay is higher. That narrows the gap between renting and buying.
The example: a 10,000-square-foot shop
For this example we used the average asking rent and the average cap rate in each market, through September 30, 2026. This is an example to show how the math works, not a quote on any real building.
Our loan assumptions:
- SBA 504 structure: 10% down from you, about 50% from a bank, and about 40% from the SBA program.
- A blended rate of about 7.2% across the bank and SBA pieces.
- 25-year payoff schedule.
| 10,000 SF shop | New Braunfels side | San Marcos side |
|---|---|---|
| Rent per month (average asking rent) | about $9,100 | about $10,400 |
| Estimated price (yearly rent ÷ cap rate) | about $1.37 million | about $1.58 million |
| Price per square foot | about $137 | about $158 |
| Your cash down (10%) | about $137,000 | about $158,000 |
| Loan payment per month | about $8,900 | about $10,200 |
| Loan paid down in year one | about $18,000 | about $21,000 |
Rents and cap rates: market data through September 30, 2026. Loan math: our estimate using early-October 2026 rate quotes.
The result. On both sides, the monthly loan payment lands within a few hundred dollars of the rent. Even with rates at a 20-year high, buying does not cost more per month than renting in this example.
And part of every loan payment is not a cost at all. It pays down what you owe. In year one, that is roughly $18,000 on the New Braunfels side and $21,000 on the San Marcos side. That amount grows every year.
A note on taxes, insurance and upkeep. Most industrial leases make the tenant pay the building’s property taxes, insurance and upkeep on top of rent. When you own, you pay those yourself. Either way, you are paying them, so we left them out of both columns. Before you compare a real building, ask whether the rent you were quoted includes those costs.
The real cost of buying: your cash
If the monthly numbers are close, what is the catch? The down payment.
In our example, you need roughly $137,000 to $158,000 in cash, plus SBA and bank fees, an appraisal, an environmental report and closing costs. That money comes out of your business. It cannot buy a truck, cover payroll in a slow month or fund a new hire.
That cash also has a cost. If it could earn 5% somewhere else, $137,000 is giving up about $6,850 a year, or about $570 a month. Add that to the loan payment and buying in our New Braunfels example costs a little more per month than renting, at first.
Over time, the picture shifts. Your loan payment stays the same for years. Your rent, if you lease, does not.
Where rents are headed
Our market data includes a rent forecast. For the example shop, it looks like this. A forecast is an educated guess, not a promise.
| 10,000 SF shop | Today | Early 2031 forecast |
|---|---|---|
| New Braunfels side, rent per month | about $9,100 | about $11,100 |
| San Marcos side, rent per month | about $10,400 | about $12,300 |
Market data and forecast through September 30, 2026.
If the forecast is close, by early 2031 the renter on the New Braunfels side pays about $11,100 a month. The owner’s loan payment is still about $8,900, a gap of about $2,200 a month. On the San Marcos side, the gap is about $2,100 a month.
This is where owning pays off. If rents keep rising as forecast, the gap between a fixed loan payment and the rent gets wider each year. And at the end of the loan, the payment goes away. A lease payment does not.
Why renting can still win right now, especially around San Marcos
Leasing has its own case. On paper, the average asking rent on the San Marcos side is about $10,400 a month for our example shop. But with 18% of the space empty, few tenants should pay full asking rent.
When landlords compete for tenants, they offer more than a lower rent. In a market like this, a business can ask for:
- Free rent. Some months at the start of the lease with no rent due.
- Build-out money. Cash from the landlord to fit the space to your business: offices, power, restrooms, a bigger door.
- A lower starting rent, or smaller yearly increases.
- Shorter terms or an early exit. Room to leave or expand if your business changes.
- A right to buy later. Some landlords will agree to give you the first chance to buy the building down the road.
Even one of those changes the math. Say you sign a five-year lease at the asking rent on the San Marcos side and get three months free. Spread over 60 months, your real monthly cost drops to about $9,900. That is below the $10,200 loan payment in our example, and you kept your $158,000.
Can you get that deal? We cannot promise any landlord will say yes. But the numbers say this is a market where asking is worth it. Hays County’s empty space is forecast to rise to about 21% by September 2027 before it starts to fall (forecast in market data through September 30, 2026). A landlord with an empty building and more competition coming has good reasons to deal.
On the New Braunfels side, landlords have less reason to bend. With about 12% empty and that number holding steady, you may get a little, but you have less pull than you would 20 miles north.
Lease or buy: a simple way to decide
Every business is different, but most owners can sort themselves with five questions.
1. How long will you stay? Buying has real costs to get in and get out. If you will be in the building seven years or more, those costs get spread thin and the fixed payment starts to pay off. If you might move or outgrow the space in three years, leasing is usually cleaner.
2. Can your business spare the cash? If the down payment would leave you thin on cash, leasing is usually the safer choice. A great building does not help a business that cannot make payroll.
3. Will you use most of the building? SBA 504 loans generally require the business to use at least 51% of an existing building. If you only need half the space, you would need to rent out the rest, and then you are a landlord too.
4. Do you need special features? Heavy power, cranes, tall doors, outside storage or a wash bay can be hard to find in a lease. If the building has to fit your work exactly, owning gives you control.
5. Which side of the line works for your crews and customers? It is usually a mistake to pick a market for its numbers alone. Pick it for your drive times, your hiring area and your customers. Then use the numbers to decide how to occupy it.
How it shakes out:
- Stay 7+ years, have the cash, New Braunfels side: buying deserves a hard look. Space is tighter, rents are rising and a fixed payment shields you from rent increases.
- Stay 7+ years, have the cash, San Marcos side: buying can still work, and sellers with empty buildings may be open to a deal. But compare it against what a landlord will give you first.
- Need your cash, or might move or grow: leasing usually fits better, and it pays to negotiate. On the San Marcos side, renters have the most room to ask.
- A middle path: sign a shorter lease at a good rate now, ideally with a right to buy. Then revisit buying when empty space fills up or rates come down.
What to do this month
If your lease ends in the next 12 to 18 months, start now. Both paths take longer than most owners expect.
- Find your lease dates. Write down when your lease ends and how much notice you must give. Many leases require six months or more.
- Get a rate quote, even if you plan to lease. A lender or SBA 504 lender can tell you what you could borrow and what the payment would be. That number tells you whether buying is even on the table.
- Count your spare cash. Work out how much you could put down without leaving your business thin.
- Price both paths on real buildings. Compare two or three buildings for lease and two or three for sale, side by side, with taxes, insurance and upkeep included.
- Talk to your landlord early. A landlord who knows you are looking may offer better terms to keep you, especially on the San Marcos side.
Questions about the loan itself
What is an SBA 504 loan? It is a federal program that helps small businesses buy or build the buildings they use. A bank lends about half, an SBA-backed lender lends about 40%, and the business puts in about 10%. Start-ups and some special-use buildings may need 15% or more. The SBA part has a fixed rate for 20 or 25 years.
Will rates come down? No one knows. Rates could fall, or they could stay high for years. Buying only because you expect to refinance later is risky. It is safer if the payment works at today’s rate.
If rates fall, can I refinance? Usually, yes, but SBA 504 loans carry a prepayment penalty for roughly the first ten years, and it shrinks each year. Ask your lender to show you what an early payoff would cost.
Are there any breaks for my kind of business? In the 2027 federal fiscal year, which began October 1, 2026, some lenders report that SBA 504 loans for manufacturing, food supply chain and rural businesses come with lower fees, worth about a quarter of a percent on the rate. Ask a lender whether your business qualifies.
Common questions
Is it a bad time to buy because rates are high?
Not necessarily. In our example, the loan payment with 10% down is about the same as the rent. The bigger questions are whether you can spare the down payment and how long you will stay.
Should I wait for prices to drop?
Prices per square foot have barely moved since 2021, because higher cap rates canceled out higher rents. They could fall further, or rents could keep pushing them up. Waiting has a cost too: every month of rent is a month of payments that builds nothing for you.
Why is there so much empty space around San Marcos?
Construction there peaked in early 2023, after a very tight market in 2021 and 2022. Much of that space opened over the following years, after demand had cooled. Businesses are still signing leases there. The market just has more space than it can fill quickly.
Will New Braunfels see the same thing?
It could, on a smaller scale. Builders on the Comal County side started more space in the last 12 months than the year before. For now, the pipeline there is smaller than around San Marcos.
Can I use a 1031 exchange to buy my own building?
A 1031 exchange lets you put off taxes on the sale of an investment property by buying another one. It generally applies to property held for investment or business use, so it can apply when your business owns its building. The rules and deadlines are strict. Talk to your tax adviser before you sell anything.
Do these numbers apply to my exact building?
No. They are county averages. A building on a busy frontage road with good truck access can rent and sell well above average. An older building with low ceilings and poor access can do worse. Always look at the exact site.
Coming next: small bay flex
Many of the business owners we talk with do not need 10,000 square feet. They need 2,000 to 5,000 square feet: a small office up front, a roll-up door in back and a place to park a trailer.
That kind of space is called small bay flex. It is often the hardest space to find in the corridor, and it behaves differently from the large warehouses that drive the averages in this article. In our next article, we will look at small bay flex on the New Braunfels and San Marcos sides: what is out there, what it costs and whether buying a single unit or a small building makes sense for a growing trade business.
Terms used
- Vacancy rate: The share of space that has no tenant.
- Absorption: The space tenants moved into, minus the space they moved out of, over a period of time.
- Cap rate: A building’s yearly income divided by its price. A higher cap rate means a lower price for each dollar of rent.
- Asking rent: The rent owners are asking for space that is open now.
- SBA 504 loan: A federal loan program for small businesses buying or building the property they use.
- Amortization: Paying off a loan over time with regular payments, part interest and part principal.
- Loan-to-value ratio: The loan amount divided by the property’s value.
- Free rent: Months at the start of a lease with no rent due.
- Tenant improvements: Work done to fit a space to a tenant’s business, often paid for in part by the landlord.
- Gross lease: A lease where the rent includes some or all of the building’s taxes, insurance and upkeep.
- Flex space: Buildings that mix office space with warehouse or shop space.
Talk it through
Every rent-or-buy decision comes down to your business, your cash and your plans. If you want to run the numbers on your own shop, on either side of the county line, talk to Rex. You can also see more about New Braunfels and San Marcos, how we help with tenant representation and buyer representation, or read our quarterly market reports.
Rate sources (early October 2026): SBA 504 rates from SomerCor and Success Capital; 10-year Treasury from Insignia Financial Services; commercial mortgage ranges from Northmarq and CommercialLoanDirect. Rates change monthly; check with a lender before relying on any figure. Population figures: U.S. Census Bureau estimates, July 2025.